Homepage ➾ Fill in Your Indiana State 104 Form

Fill in Your Indiana State 104 Form

Modify Form

Similar forms

The Indiana State Form 102 is a property tax return for residential real estate. Similar to Form 104, it requires taxpayers to report the assessed value of their property. Both forms have filing deadlines and penalties for late submissions. The Form 102 specifically focuses on real property, while Form 104 addresses business tangible personal property. Taxpayers must provide accurate information to ensure compliance with state regulations, highlighting the importance of transparency in property valuation.

Form 103, also known as the Business Personal Property Tax Return, is closely related to Form 104. It is used by businesses to report personal property used in their operations. Like Form 104, it includes sections for reporting assessed values and requires submission to the appropriate local authority. Both forms emphasize the need for accurate reporting and may impose penalties for undervaluation or late filing. However, Form 103 is typically used for larger businesses or those with more complex property holdings.

The Indiana Form 105 serves as a summary form for taxpayers with properties in multiple taxing districts. This form is required for those who must file separate returns in different districts, similar to the requirements outlined in Form 104. Both forms require detailed reporting of property locations and values. Form 105 streamlines the process for taxpayers who operate across various jurisdictions, ensuring compliance with local tax laws while maintaining clarity in reporting obligations.

Lastly, Form 101 is used for reporting recreational personal property not subject to excise tax. While it differs from Form 104 in that it focuses on non-business assets, both forms require taxpayers to accurately disclose property details. Each form has specific instructions and deadlines, reinforcing the importance of timely reporting. The distinction lies in the type of property being reported, yet both contribute to the overall assessment and taxation process within Indiana.

FAQ

What is the Indiana State 104 form and who needs to file it?

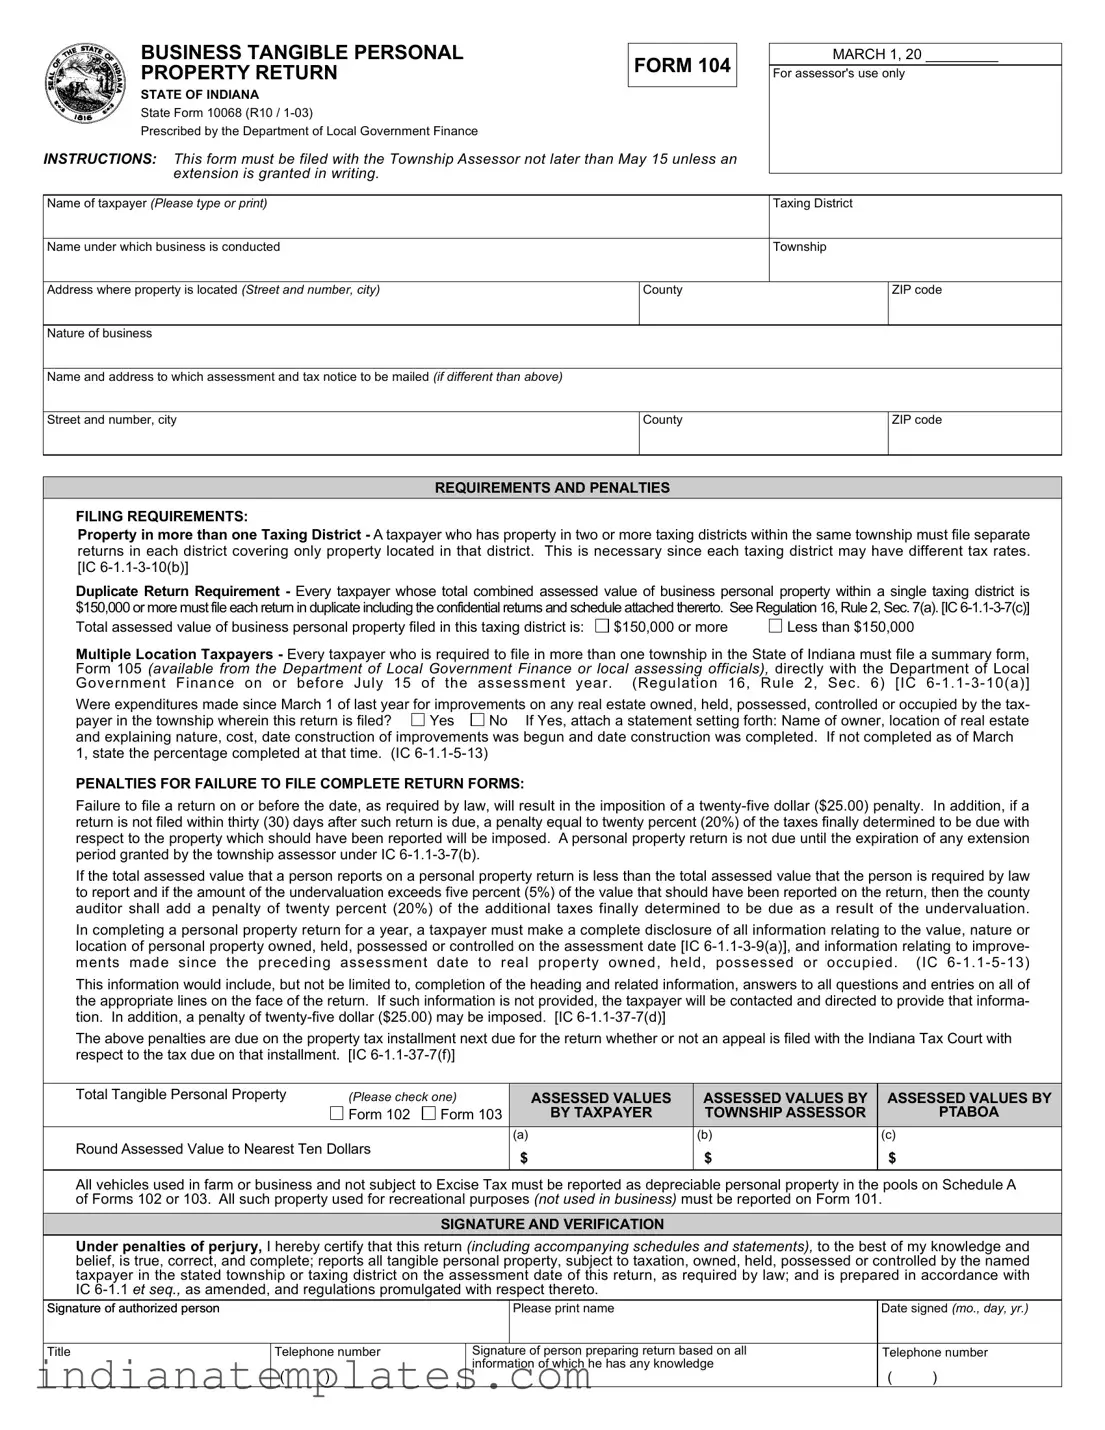
The Indiana State 104 form is a property return form specifically designed for reporting business tangible personal property. It must be filed by any taxpayer who owns, holds, possesses, or controls tangible personal property used for business purposes within the state of Indiana. This form is required to be submitted to the Township Assessor by May 15 of each year, unless a written extension has been granted. Taxpayers with property in multiple taxing districts must file separate returns for each district, as tax rates may vary.

What are the penalties for failing to file the Indiana State 104 form on time?

Failure to file the Indiana State 104 form by the deadline can result in significant penalties. A taxpayer who does not file by the due date will incur a penalty of $25. If the return is not submitted within 30 days after the deadline, an additional penalty of 20% of the taxes due may be assessed. Furthermore, if a taxpayer undervalues their property by more than 5%, a penalty of 20% on the additional taxes due may also be imposed. These penalties are applied to the property tax installment next due, regardless of any appeals filed with the Indiana Tax Court.

What information is required to complete the Indiana State 104 form?

To complete the Indiana State 104 form, taxpayers must provide comprehensive information about their tangible personal property. This includes the name of the taxpayer, the nature of the business, the address of the property, and the assessed value of the property. Taxpayers must also disclose any improvements made to real estate since the last assessment date. It is crucial to provide accurate and complete information, as incomplete returns may lead to additional penalties and the requirement to submit further documentation.

What should a taxpayer do if they have property in more than one taxing district?

If a taxpayer has tangible personal property in more than one taxing district, they must file separate returns for each district. Each return should only cover property located within that specific district. Additionally, taxpayers who need to file in multiple townships are required to submit a summary form, known as Form 105, to the Department of Local Government Finance by July 15 of the assessment year. This ensures that all property is accurately reported and assessed according to the appropriate local tax regulations.

Common mistakes

Filling out the Indiana State 104 form can be straightforward, but many people make common mistakes that can lead to penalties or delays. One significant error is missing the filing deadline. The form must be submitted to the Township Assessor by May 15. If you miss this date, a penalty of $25 may be imposed. It’s essential to mark your calendar and ensure that your form is submitted on time.

Another frequent mistake involves not filing separate returns for properties located in multiple taxing districts. If you own property in more than one district within the same township, you must file separate returns for each district. Failing to do so can complicate your tax situation and may result in additional penalties.

People also often overlook the requirement to file in duplicate if their total assessed value of business personal property is $150,000 or more. Not providing the necessary duplicate returns can lead to issues with compliance and may result in penalties. Be sure to check your total assessed value and submit the correct number of forms.

Inadequate disclosure of property details is another common pitfall. Taxpayers must provide complete information regarding the value, nature, and location of their personal property. If you fail to include all required information, you may be contacted for clarification, which could delay your assessment.

Many individuals forget to report improvements made to real estate since the last assessment date. If you made any enhancements, you need to attach a statement detailing the nature, cost, and completion status of those improvements. Omitting this information can lead to penalties for undervaluation.

Another mistake is not providing accurate contact information. Ensure that the name and address for mailing tax notices are correct. If you provide incorrect details, you may miss important communications regarding your tax assessment.

Some taxpayers neglect to sign the form. The signature certifies that the information provided is accurate and complete. Without a signature, the return may be considered invalid, leading to further complications.

Finally, failing to double-check for errors before submission can be detrimental. Simple mistakes in calculations or missing information can result in penalties or delays. Take the time to review your form thoroughly to ensure accuracy and completeness.

Indiana State 104 Preview
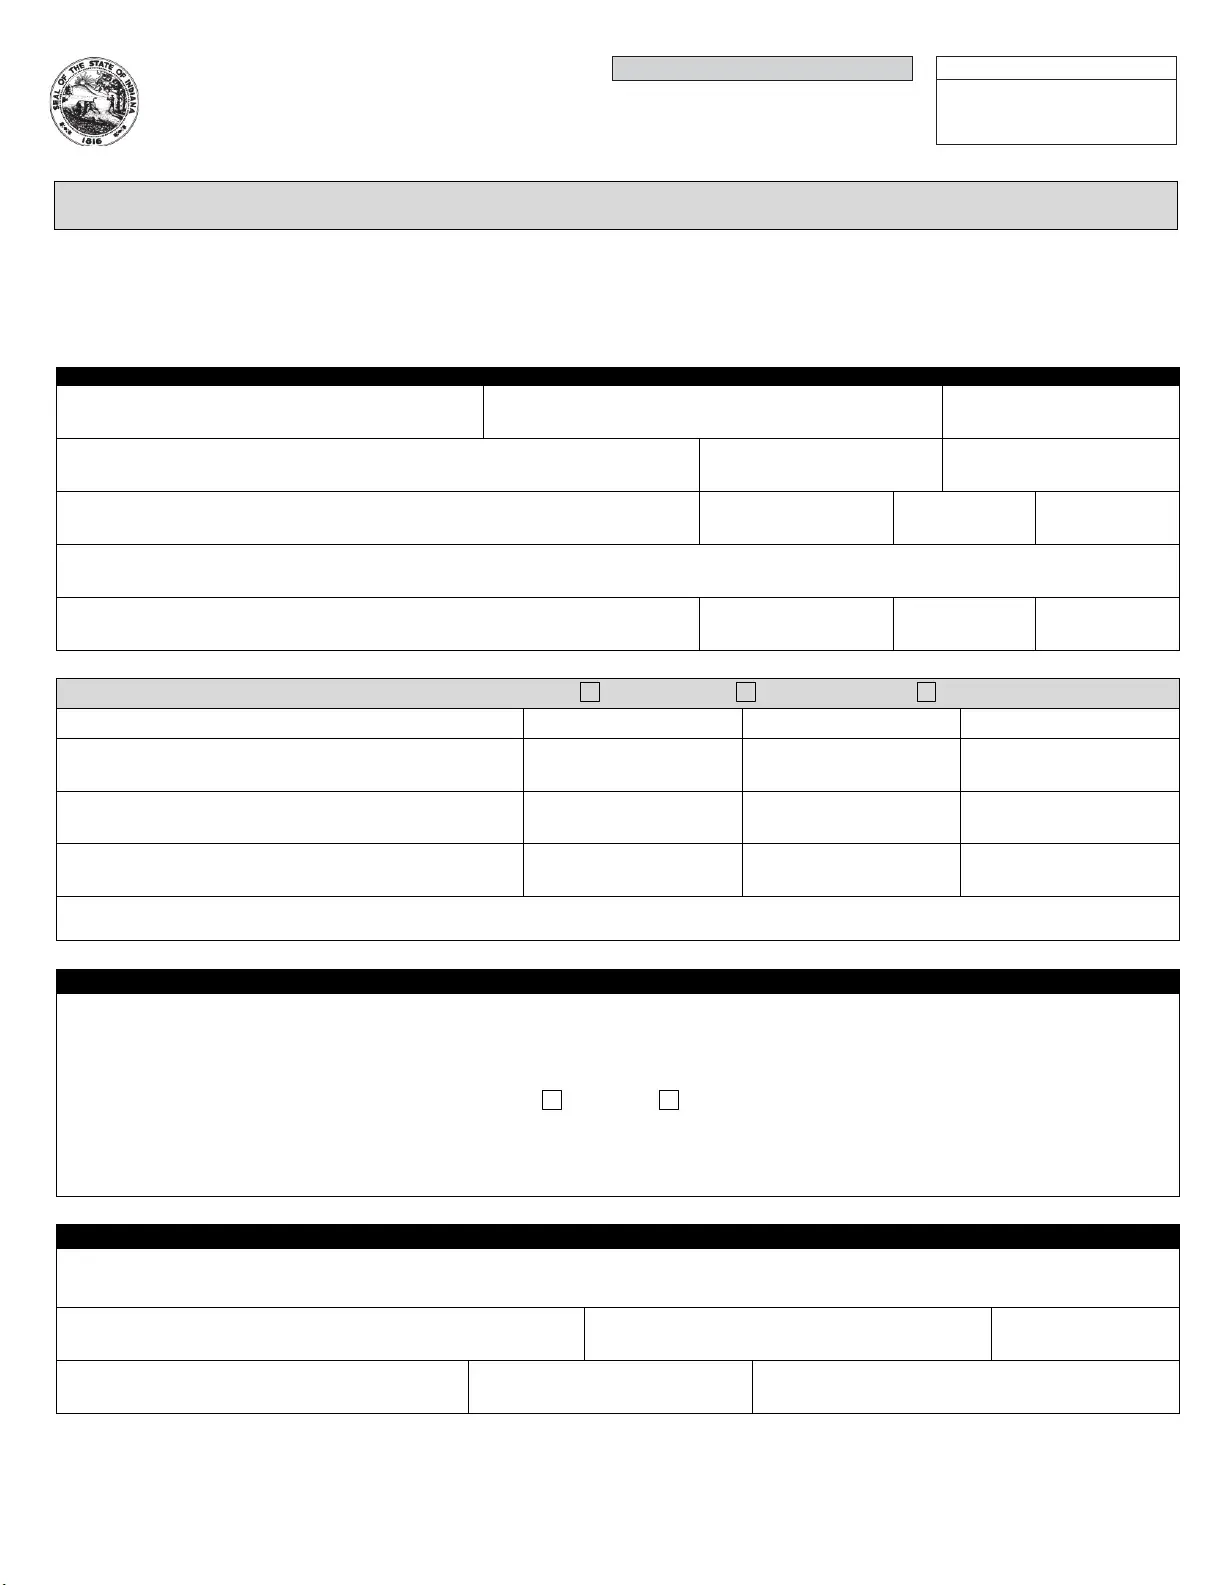
BUSINESS TANGIBLE PERSONAL
PROPERTY RETURN
State Form 10068 (R31 / 12-25)
Prescribed by the Department of Local Government Finance
FORM 104
JANUARY 1, 2026
For Assessor's Use Only
This form is filed with Form 102, Form 103 – Short, or Form 103 – Long. Signatures on both this form and the corresponding Form 102 or Form
103 are required per 50 IAC 4.2-2-9(e).
☐ Yes, I am declaring the $2,000,000 exemption and will also claim the exemption on Form 102, Form 103 – Short, or Form 103 – Long.
NOTE: If you filed a return and claimed this exemption in a previous assessment year and you continue to qualify for this exemption, no return is required.
INSTRUCTIONS: This form must be filed with the township assessor, if any, or the county assessor of the county in which the property is located not later
than May 15, 2026, unless an extension of up to thirty (30) days is granted in writing for the county where the property has tax situs.
SECTION I
Name of Taxpayer
Name Under Which Business Is Conducted
DLGF Taxing District Number
Nature of Business
County
Township
Address Where Property Is Located (number and street)
City
ZIP Code
Name to Which Assessment and Tax Notice Should Be Mailed (if different than above)
Mailing Address (number and street) (if different than above)
City
ZIP Code
TOTAL TANGIBLE PESONAL PROPERTY (Please check one) Form 102 Form 103 – Short Form 103 – Long
SUMMARY (round all numbers to nearest ten dollars)
REPORTED BY TAXPAYER
CHANGE BY ASSESSOR
CHANGE BY COUNTY BOARD
Schedule A - Personal Property
$
$
$
Deduction per Form 102-ERA, Form 103 ERA, or Form 103-CTP -
$
$
$
Final Assessed Value =
$
$
$
All vehicles used in farm or business and not subject to Excise Tax must be reported as depreciable personal property in the pools on Schedule A or Forms 102 or 103.
FILING REQUIREMENTS
Property in more than one Township – Due to varying tax rates, a taxpayer who has property in two or more townships must file any additional returns
with the county assessor. (IC 6-1.1-3-10)
Were expenditures made since the last assessment date for improvements on any real property owned, held, possessed, controlled, or occupied by the
taxpayer in the township wherein this return is filed?
Yes
No
If Yes, attach a statement setting forth the name of owner, location of the real property, an explanation of the nature, cost, date on which construction of
improvements was begun, and date on which construction was completed. If not completed as of January 1, state the percentage completed at that time.
(IC 6-1.1-5-13)
SIGNATURE AND VERIFICATION
Under penalties of perjury, I hereby certify that this return (including any accompanying schedules and statements), to the best of my knowledge and belief, is true, correct, and
complete; if applicable, reports all tangible personal property subject to taxation owned, held, possessed or controlled by the named taxpayer in the stated township or taxing
district on the assessment date, as required by law; and is prepared in accordance with IC 6-1.1 et seq., as amended, and regulations promulgated with respect thereto.
Signature of Authorized Person
Printed Name of Authorized Person
Date (month, day, year)
Title of Authorized Person
Telephone Number
( )
Email of Authorized Person
Page 1 of 2
PENALTIES FOR FAILURE TO FILE COMPLETE AND ACCURATE FORMS
Failure to file a return on or before May 15, or be granted an extension of time to file a return, as required by law, will result in the imposition of a twenty-
five-dollar ($25) penalty to the filer’s next property tax installment. Effective May 1, 2024, an additional penalty will be added to the overall tax liability, as
calculated below:
o If the return is filed before November 15, the lesser of 10% of the taxes due or $10,000; or
o If the return is filed after November 15, the lesser of 20% of the taxes due or $50,000.
If the total assessed value that a person reports on a personal property return is less than the total assessed value that the person is required by law to
report and if the amount of the undervaluation exceeds five percent (5%) of the value that should have been reported on the return, then the county
auditor shall add a penalty of twenty percent (20%) of the additional taxes finally determined to be due as a result of the undervaluation. [IC 6-1.1-37-7(e)]
In completing a personal property return for a year, a taxpayer must make a complete disclosure of all information relating to the value, nature, or location
of personal property owned, held, possessed, or controlled on the assessment date [IC 6-1.1-3-9(a)], and information relating to improvements made
since the preceding assessment date to real property owned, held, possessed, or occupied. (IC 6-1.1-5-13) This information would include, but not be
limited to, completion of the heading and related information, and answers to all questions and entries on all of the appropriate lines on the face of the
return. If such information is not provided, the taxpayer will be contacted and directed to provide that information. In addition, a penalty of twenty-five
dollars ($25) shall be imposed. [IC 6-1.1-37-7(d)]
The above penalties are due on the property tax installment next due for the return, whether or not an appeal is filed pursuant to Ind. Code § 6-1.1-15-5
with respect to the tax due on that installment. [IC 6-1.1-37-7(g)]
FILING BASICS
The Personal Property Online Portal (PPOPIN) will be discontinued effective January 1, 2026. While no new filings will be accepted, previous filings will
still be accessible for historical data at: ppopin.in.gov.
Indiana’s personal property tax system is a self-assessment system, so it is the taxpayer’s responsibility to file this form in a timely manner. The forms are
also available online on the Department’s website: https://www.in.gov/dlgf/forms/dlgf-forms/. To learn more about Indiana’s personal property tax system,
go to: https://www.in.gov/dlgf/assessments/personal-property/.
Personal property must be assessed in each taxing district where property has a tax situs.
For taxpayers with less than $2,000,000 in acquisition costs to be reported within a county, Ind. Code § 6-1.1-3-7.2 exempts this property. If you are
claiming this exemption through another form, you must also file Form 104. If you filed a return and claimed this exemption in the previous assessment
year and you continue to qualify for this exemption, no return is required. To establish an exemption in a new county, new or existing businesses must file
a personal property return during their first year in that new county.
Depreciable personal property that is placed in service after January 1, 2025, is not subject to the 30% minimum valuation limitation—except when the
property is situated within a tax increment finance (TIF) allocation area whose base assessed value was established prior to January 1, 2025 (IC
6-1.1-3-29(c)).
Taxpayers may request up to a thirty (30) day extension to file their return. The written request should be sent to the assessor before the filing deadline of
May 15, 2026, and should include a reason for the request. The assessor may, at their discretion, approve or disapprove the request in writing.
Taxpayers who discover an error was made on their original timely filed personal property tax return have the right to file an amended return. The
amended return must be filed within twelve (12) months of the due date or the extended due date (if up an extension was granted) of their original return.
The deadline to amend this return, if no extension has been granted, is May 17, 2027.
If you hold, possess, or control not-owned personal property on the assessment date, you have a liability for the taxes imposed for that year unless you
establish that the property is to be assessed to the owner. This is done by completing Form 103 – N, attaching it to Form 103 – Long, and filing it with the
assessor. A taxpayer declaring the exemption on Page 1 of this form may, as deemed necessary by the applicable assessor, need to file Form 103 – O or
Form 103 – N, as applicable, to verify that the individual is the appropriate taxpayer to claim the exemption.
NOTE: Failure to properly disclose lease information may result in a double assessment. (IC 6-1.1-2-4(a))
No return is required if personal property previously reported in this taxing district last year has been sold or relocated. To reduce the possibility of an
estimated assessment, taxpayers may elect to notify the assessor of such changes. If a closed business retains property within the taxing district, an
assessment may still be required and is determined on a case-by-case basis.
Page 2 of 2